Author Archive
How Cyber Savvy Are You?
How Cyber Savvy Are You?
Cyberattacks are America’s fastest-growing crime. Review these tips for keeping your personal information safe.
Do you know the difference between a vishing and a smishing attack? Or that spear phishing doesn’t happen in the ocean? Cyberattacks are the fastest-growing crime in the U.S. – and they cause personal and business devastation every day.
Because technology – and the schemes to manipulate users – changes so quickly, it’s important to be in the know. See how well you stack up:
What’s the No. 1 type of cyberattack?
Ransomware, and experts say it’s a growing concern. A type of malware that encrypts a victim’s files, ransomware allows the attacker to demand money to restore access to important documents or photos saved on your hard drive.
What’s the difference between phishing and spear phishing?
Phishing is the attempt to gain usernames, passwords and credit card numbers by impersonating a trustworthy sender in an email or other digital communication. This might entail disguising their email to look like someone you know or including a link to a fake website to trick you into entering private information.
Spear phishing is tailored to one individual and may mention an upcoming trip or a child’s name, for example.
How many different versions of phishing are there?
Unfortunately, there’s a growing list of phishing scams. But there are two popular ones to be aware of:
Vishing is a voice version of phishing. The caller pretends to be from law enforcement, the government or a bank and will try to gain access to Social Security numbers, account numbers or other personal information by asking the victim questions for “verification” purposes.
Smishing is an SMS (or text) version of phishing. You know those automated alerts from the credit card company or PayPal? It might be disguised in that way.
Next steps: How to protect yourself
Criminals are getting more sophisticated. But you can combat the risk by putting these protections in place:
- Be diligent about not sharing information. It might be fun to answer a silly quiz on Facebook, but criminals can use this to gain access to security question answers, like your first dog’s name or the street you grew up on.
- Use multifactor authentication, which requires two or more authentication factors to access devices, applications or online accounts.
- Browse in “incognito” mode so local search history is not stored and cookies are blocked.
- Use secure passwords that include a mix of uppercase and lowercase letters, numbers and symbols. Make sure each password is at least 12 characters and doesn’t contain personally identifiable information. Pro tip: Use a password management app to help you create and organize them.
- Use a virtual private network (VPN) to create an encrypted connection between your devices and the internet that hides your online activity.
- Regularly back up files to a local external server or a cloud server. At least you’d have access to all your files in case of an attack.
- Look for the “s” in “https.” It stands for secure, and it must be there when you’re entering your credit card or banking information to make a purchase. This alone does not mean a site is secure, but it certainly should be a red flag if it is not there.
- If you are unsure if a call you answer is a vishing scam, hang up and dial the company you believe is trying to reach you – for example, your bank – directly.
Sources: pcmag.com; us.norton.com
Links are being provided for information purposes only. Raymond James is not affiliated with and does not endorse, authorize or sponsor any of the listed websites or their respective sponsors. Raymond James is not responsible for the content of any website or the collection or use of information regarding any website’s users and/or members. Raymond James does not provide tax or legal services. Please discuss these matters with the appropriate professional.
Day One of the Rest of Your Life
Day One of the Rest of Your Life
Visualizing what you want in retirement before you get there may lead to greater fulfillment.
Like all major life events, transitioning to retirement will be an adjustment. It’s important that you’re ready for that change, so you can step into your new life with confidence. One day you may go from your seat at the top as a powerful executive to a lounge chair in your living room. Without your career to define you, you’ll want to discover new meaning.
Finding the answer takes a lot of preparation – emotionally, physically and financially – and a lot of thought. While the financial component is critical to a sustainable retirement, so is your quality of life. Too few people consider the psychological factors. If you can start visualizing your ideal retirement now, you’ll set yourself up for a more satisfying and fulfilling day one.
Thinking ahead
Experts say a steady transition into retirement makes for a more successful one. One psychologist suggests focusing on these key areas to consider the life you’re looking for.
Focus on enhancing relationships. Establish weekly game nights with friends or Sunday dinners with family, for example. Be sure to maintain or expand your social life and stay connected. Studies show having friends and family for entertainment and support significantly enhances a retiree’s quality of life.
Keep your mental and physical health a priority. Set up and keep wellness appointments and exercise daily. And don’t forget to relax. You’ve earned it! Take time for yourself when you need to, and nap when you feel like it.
Make sure you feel as financially secure as possible. Ideally, you’ve been working toward this goal throughout your career. If you need to clarify your retirement income stream, do that now with the help of your professional advisor.
Stay young at heart. Take up an old hobby or find a new one, learn welding or Spanish, play a new instrument. Or, if you really want to dive in, consider that Harvard and Stanford have established learning programs for leaders who had distinguished careers. The point is to plan and embark on a new adventure every week, even if that’s tutoring an elementary student in math or trying a new restaurant. Find something that keeps your brain firing.
Be kind. Acts of kindness make everyone feel good. Volunteer, donate time or money, or contribute to your community in another way.
As you work to home in on the activities that will help you live well on a day-to-day basis, you’ll want to make sure your family and advisors can picture your vision too, and that the details are included in a well-documented financial plan. Being able to clearly articulate your vision helps to prioritize your needs, wants and wishes in order to figure out how to make them a reality.
Next steps
As you approach retirement:
- Visualize how you’d like to spend your days in retirement without a schedule to dictate your day
- Consider each psychological/emotional aspect of your life to ensure it’s being fulfilled by your retirement plans
- Speak to your advisor to ensure the financial plan you have in place will make your vision a reality
Sources: ucsfhr.ucsf.edu
Links are being provided for information purposes only. Raymond James is not affiliated with and does not endorse, authorize or sponsor any of the listed websites or their respective sponsors. Raymond James is not responsible for the content of any website or the collection or use of information regarding any website’s users and/or members. Raymond James does not provide tax or legal services. Please discuss these matters with the appropriate professional.
The Scoop on Backdoor Roth IRAs
– Evan Shear, CFP® and W. Dale Crossley, Jr., JD, CWS®, CrossleyShear Wealth Management
If you’re in a higher-income bracket and have been saving for retirement, you likely have a traditional IRA in your portfolio. There are two types of IRAs for individual investors: traditional and Roth. Meanwhile, businesses can set up SEP IRAs or SIMPLE IRAs. However, higher-income individual investors can also set up what are called back door Roth IRAs. You may also be able to rollover your 401k into a Roth IRA.
We receive many questions about the tax advantages of the various types of IRAs. Routinely, we help our clients determine the feasibility of converting traditional IRA or 401k assets to Roth IRA assets, even if they earn more than the income limits determined by the IRS.
Only two things are guaranteed in life, and one of them is taxes.
If you're saving for retirement and looking for efficient tax strategies, traditional IRAs can be a great choice. They're a valuable tool to save money for your golden years.
If you're okay with making after-tax contributions for retirement, a Roth IRA may be a better choice.
Let's start with a quick overview of IRAs.
Traditional and Roth IRAs
According to the Internal Revenue Service (IRS), "An individual retirement arrangement (IRA) is a tax-favored personal savings arrangement, which allows you to set aside money for retirement." While these accounts can’t be held jointly with your spouse, your spouse can be a beneficiary in the event of your death.
- Traditional IRAs allow you to save for retirement with pre-tax funds. If you make early withdrawals, you incur fees and tax penalties.
- Roth IRAs require after-tax contributions. There are no taxes or penalties if you withdraw funds after the Roth IRA has been established for 5 years. Otherwise, you will be responsible for paying taxes and penalties. It’s important to know that the Roth five-year rule applies to the following instances: you withdraw account earnings, convert a traditional IRA to a Roth, and if a beneficiary inherits a Roth IRA.
IRAs have income limits, however, and we'll get to that in a moment.
Each system has advantages and disadvantages, depending on your tax bracket and retirement saving goals. However, both types of IRAs will likely earn better interest than a savings account and are virtually risk-free compared to other investments.
Traditional IRAs: Great for Keeping Your Taxable Income Low
The IRS strictly limits contributions to traditional IRAs. Currently, that cap is $6,000 per year if you're under 50. If you're on the cusp of a higher tax bracket and can stay in a lower bracket by opening a traditional IRA, it may be the perfect time to invest.
Roth IRAs: Retirement Savings When You Can Manage the Tax Bill
According to the IRS, contributions to a Roth IRA aren't tax-deductible. You don't report contributions on your tax return. Therefore, qualified distributions or distributions that are a return of excess contributions (and withdrawn by the tax-filing deadline in April) aren't taxed. Roth IRAs must be designated as such when they're set up.
The challenge for many high earners, though, is Roth IRA income limits. For the 2020 tax year, the government allows only married couples filing jointly with modified adjusted gross incomes below $206,000 or $139,000 for a single individual to contribute to a Roth IRA. In 2021, the limits are $208,000 / $140,000.
However, you can transfer funds from a traditional IRA to a Roth IRA! It's called a backdoor Roth IRA, and you'll need to pay some taxes to get it done.
The Scoop on Backdoor Roth IRAs
According to the IRS, "Regardless of the amount of your adjusted gross income, you may be able to convert amounts from either a traditional [IRA]into a Roth IRA."
In other words, a backdoor Roth IRA allows high-income individuals to sidestep Roth's income limits.
Here's how it works:
- You put money in a traditional IRA
- Convert contributed funds into a Roth IRA.
- Pay some taxes on those funds.
- You now have a “backdoor” Roth IRA
Even though your earnings exceed the Roth IRA income limits, this back door allows you to grow your savings tax-free!
That said, you’ll want to take steps to minimize costly mistakes and reduce your legal liabilities. Before making any major moves with your retirement savings, be sure to talk to your financial advisor as well as qualified tax professional and consider these drawbacks to backdoor IRAs:
- Don’t forget, money converted from a traditional IRA to a Roth IRA falls under a Roth five-year rule.
- So, if you need that money soon and can’t wait five years to withdraw it, you may owe taxes and a 10% penalty.
- The withdrawal may push you into a higher tax bracket. You want to avoid that, so only convert enough funds to keep you below that threshold.
In addition, if you're thinking of using money from your withdrawal to pay the required taxes, don’t. You'll be sacrificing any interest your money could be earning. There's also a risk if you're under 59-½: you may incur a 10% early withdrawal penalty.
Rollover your 401k into a Roth IRA
In addition, you may be able to rollover your 401k directly into a Roth IRA if you meet certain requirements.
- You separate from your employer, retire, or in some cases, if you are 59-½.
- Depending on your current employers’ rules, they may permit an in-service rollover, but it’s best to discuss the pros and cons of this option with your financial advisor.
Like the traditional IRA conversion, you’ll owe taxes, so it’s important to carefully review this strategy with your financial advisor as well as qualified tax professional to determine whether paying taxes now, to reduce the burden later, is truly the best option for you.
At CrossleyShear Wealth Management, we know you've worked hard to plan for a retirement you'll enjoy. If you'd like to learn more about whether a backdoor Roth IRA, 401k rollover or traditional IRA is the best financial strategy for you, we're here to help. Schedule an appointment today.
The information has been obtained from sources considered to be reliable, but we do not guarantee that the foregoing material is accurate or complete. Any opinions are those of the author and not necessarily those of Raymond James. Expressions of opinion are as of this date and are subject to change without notice. There is no guarantee that these statements, opinions or forecasts provided herein will prove to be correct. Any information is not a complete summary or statement of all available data necessary for making an investment decision and does not constitute a recommendation. Investing involves risk and you may incur a profit or loss regardless of strategy selected. Past performance does not guarantee future results.
Contributions to a traditional IRA may be tax-deductible depending on the taxpayer's income, tax-filing status, and other factors. Withdrawal of pre-tax contributions and/or earnings will be subject to ordinary income tax and, if taken prior to age 59 1/2, may be subject to a 10% federal tax penalty.
Like Traditional IRAs, contribution limits apply to Roth IRAs. In addition, with a Roth IRA, your allowable contribution may be reduced or eliminated if your annual income exceeds certain limits. Contributions to a Roth IRA are never tax deductible, but if certain conditions are met, distributions will be completely income tax free.
Unless certain criteria are met, Roth IRA owners must be 59½ or older and have held the IRA for five years before tax-free withdrawals are permitted. Additionally, each converted amount may be subject to its own five-year holding period. Converting a traditional IRA into a Roth IRA has tax implications. Investors should consult a tax advisor before deciding to do a conversion.
While we are familiar with the tax provisions of the issues presented herein, as Financial Advisors of RJFS, we are not qualified to render advice on tax or legal matters. You should discuss tax or legal matters with the appropriate professional.
Any opinions are those of the author and not necessarily those of Raymond James. Expressions of opinion are as of this date and are subject to change without notice. There is no guarantee that these statements, opinions or forecasts provided herein will prove to be correct. Any information is not a complete summary or statement of all available data necessary for making an investment decision and does not constitute a recommendation. Investing involves risk and you may incur a profit or loss regardless of strategy selected. Past performance does not guarantee future results.
*Trust services offered through Raymond James Trust, N.A., a subsidiary of Raymond James Financial, Inc. CrossleyShear Wealth Management and CSsports are not registered broker dealers and are independent of Raymond James Financial Services. Securities offered through Raymond James Financial Services, Inc. Member FINRA/SIPC.
Investment advisory services are offered through Raymond James Financial Services Advisors, Inc. Certified Financial Planner Board of Standards Inc. owns the certification marks CFP®, CERTIFIED FINANCIAL PLANNER™, CFP® (with plaque design) and CFP® (with flame design) in the U.S., which it awards to individuals who successfully complete CFP Board’s initial and ongoing certification requirements.
Securities are offered through Raymond James Financial Services, Inc., member FINRA/SIPC. Investment advisory services offered through Raymond James Financial Services Advisors, Inc. CrossleyShear Wealth Management is not a registered broker/dealer and is independent of Raymond James Financial Services.
CrossleyShear Wealth Management’s Evan Shear and Dale Crossley Named to Forbes’ 2021 List of Top Wealth Advisors
HEATHROW/MERRITT ISLAND, FLORIDA, February 23, 2021 – CrossleyShear Wealth Management (CrossleyShear), a team of premier financial planning and wealth management advisors, announced today that both founding partners, Evan Shear and Dale Crossley, have been named to Forbes Magazine’s prestigious list of America’s Best-in-State Wealth Advisors. The annual ranking spotlights more than 5,000 advisors who are researched, interviewed, and assigned a ranking based on an algorithm of qualitative and quantitative criteria.
“It’s truly humbling for me and the entire CrossleyShear team to be recognized for a fourth consecutive year with the tremendous honor. This achievement clearly demonstrates our entire team’s passion for providing our clients with the very best in care and financial planning expertise,” stated Evan Shear, Co-Founder and Branch Manager of CrossleyShear Wealth Management, and CERTIFIED FINANCIAL PLANNER™ professional. “Our focus is always first and foremost on our clients. Helping them succeed and making a positive impact on their lives each and every day is the core of our mission,” added W. Dale Crossley, Jr., JD, CWS®, Co-Founder of CrossleyShear Wealth Management, Branch Manager and Financial Planner – RJFS.
The Forbes ranking of Best-In-State Wealth Advisors, developed by SHOOK Research, is based on an algorithm of qualitative criteria, mostly gained through telephone and in-person due diligence interviews, and quantitative data. Those advisors that are considered have a minimum of seven years of experience, and the algorithm weights factors like revenue trends, assets under management, compliance records, industry experience and those that encompass best practices in their practices and approach to working with clients. Portfolio performance is not a criteria due to varying client objectives and lack of audited data. Out of approximately 32,725 nominations, more than 5,000 advisors received the award.
To learn more about CrossleyShear Wealth Management and the practice’s financial planning and wealth management solutions, visit CrossleyShear.com. For more information about CSsports, visit CSsports.net.
About CrossleyShear Wealth Management | Since 1998, CrossleyShear Wealth Management has served as a premier financial planning team dedicated to helping provide clients and families with innovative financial solutions and wealth management strategies. With offices in Heathrow and Merritt Island, Florida, their tailored customer care philosophy and customized planning process helps empower its clients to achieve their financial goals and financial independence. The company’s CSsports division exclusively serves the unique needs of professional athletes – before, during and after their sports career – providing customized solutions ranging from everyday spending advice and retirement planning to managing investments, insurance and business planning. For more information about CrossleyShear Wealth Management and CSsports, visit CrossleyShear.com.
1515 International Parkway, Suite 2019, Heathrow, FL 32746 | 407.215.7575
2395 N. Courtenay Parkway, Suite 201, Merritt Island, FL 32953 | 321.452.0061
CrossleyShear Wealth Management and CSsports are not registered broker dealers and are independent of Raymond James Financial Services. Securities offered through Raymond James Financial Services, Inc. Member FINRA/SIPC.
Investment advisory services are offered through Raymond James Financial Services Advisors, Inc. Certified Financial Planner Board of Standards Inc. owns the certification marks CFP®, CERTIFIED FINANCIAL PLANNER™, CFP® (with plaque design) and CFP® (with flame design) in the U.S., which it awards to individuals who successfully complete CFP Board’s initial and ongoing certification requirements.
The Forbes ranking of Best-In-State Wealth Advisors, developed by SHOOK Research, is based on an algorithm of qualitative criteria, mostly gained through telephone and in-person due diligence interviews, and quantitative data. Those advisors that are considered have a minimum of seven years of experience, and the algorithm weights factors like revenue trends, assets under management, compliance records, industry experience and those that encompass best practices in their practices and approach to working with clients. Portfolio performance is not a criteria due to varying client objectives and lack of audited data. Out of approximately 32,725 nominations, more than 5,000 advisors received the award. This ranking is not indicative of an advisor's future performance, is not an endorsement, and may not be representative of individual clients' experience. Neither Raymond James nor any of its Financial Advisors or RIA firms pay a fee in exchange for this award/rating. Raymond James is not affiliated with Forbes or Shook Research, LLC. Please visit https://www.forbes.com/best-in-state-wealth-advisors for more info.
Rigatoni alla Carbonara
Rigatoni alla Carbonara
Cooking Time: 30 minutes
Serves: 4
Difficulty Level: Easy
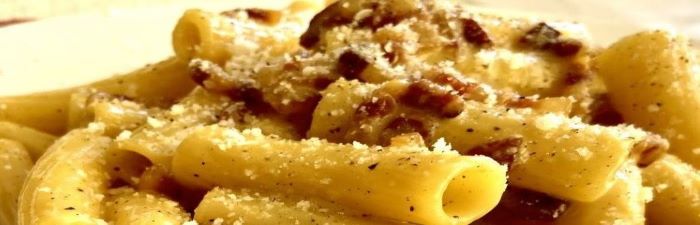
This is a classic Roman recipe. It’s impossible to go to a random ‘trattoria’ in Rome and not find Carbonara on the menu. Nevertheless, did you know that this dish was actually born in the US? In fact, its first recipe appears in “An Extraordinary Guide to What’s Cooking on Chicago’s Near North Side”, in 1952! If you think about it, the combination between bacon (Guanciale) and eggs, it’s something really American. Here is the recipe for the authentic Carbonara, the only one, that you need to follow carefully to turn out perfectly for your guests!
Ingredients
380 gr (13.4 oz) Rigatoni dry pasta
150 gr (5.2 oz) Guanciale DOP – whole piece best; alternatively, 0.25 inches thick slices. If you can’t find Guanciale, go for Pancetta or Bacon.
5 egg yolks
30 gr (1 oz) Pecorino romano DOP cheese
20 gr (0.7 oz) Parmesan Reggiano DOP
Black Peppercorns (half tablespoon)
Mediterranean Sea Salt
Directions
Bring the water to a boil in a large-sized pot.
On a cutting board, cut the Guanciale (or Pancetta) into strips of about 0.5 inches long and ¼ inch thick, taking care to dispose of the rind.
With the help of a meat mallet, crush the black peppercorns to get a coarsely ground black pepper.
Separate the yolks from the egg whites. Pour the 5 yolks into a bowl and add almost all of the Pecorino Romano DOP cheese (leaving about a tablespoon for the final garnishment), the Parmesan Reggiano DOP and the black pepper. Mix the sauce with a whisk until you get a thick cream.
In a large-sized sauté pan, add a tablespoon of EVOO and the Guanciale strips. Cook over medium heat until the Guanciale is golden brown. Turn off the burner and set aside.
Salt the boiling water, and add the rigatoni. After about 3 minutes, add half of a ladle of cooking water to the yolk sauce and mix with a whisk until a semi-liquid sauce is reached.
Drain the rigatoni when it is “al dente” (firm to the tooth) with the help of a skimmer (do not dispose of the cooking water) and put the pasta in the pan with the Guanciale, add one or two ladles of cooking water and stir on high heat for about 1 minute. Now turn off the burner (the rigatoni must have absorbed almost all the sauce). Let it cool for about 45 seconds, then pour the yolk sauce and stir with a wooden spoon (this will prevent the egg yolks from becoming scrambled).
Serve and enjoy your Carbonara immediately with the final garnishment of Pecorino and ground black pepper.
This dish pairs perfectly with Chardonnay or Frascati Superiore.
Article printed from LA CUCINA SABINA: https://www.lacucinasabina.com
URL to article: https://www.lacucinasabina.com/recipe/rigatoni-alla-carbonara/
Links are being provided for information purposes only. Raymond James is not affiliated with and does not endorse, authorize or sponsor any of the listed websites or their respective sponsors. Raymond James is not responsible for the content of any website or the collection or use of information regarding any website’s users and/or members. Raymond James does not provide tax or legal services. Please discuss these matters with the appropriate professional.