Author Archive
From the Desk of Dale Crossley and Evan Shear
From the Desk of Dale Crossley and Evan Shear
We hope this email finds you and your loved ones safe and well. For our last 2021 edition of The Journey, you’ll find helpful articles on Medicare open enrollment, Social Security increases and a delicious chicken cacciatore recipe. We'd like to wrap up the year with last-minute tax and Required Minimum Distribution (RMD) reminders and a bit about the recently passed infrastructure bill.
Before the year ends, it’s a good time to make sure that you’ve set yourself up properly from a tax standpoint for 2022. Check with us to see if you can benefit from tax-loss harvesting which is selling a losing investment to offset gains. It’s also important to pay attention if you’re at or near the next tax bracket. If so, we can discuss ways that you can reduce taxable income now as the year comes to an end. We also want to remind you of RMDs for 2021. Last year, there was a special RMD waiver due to the CARES Act, but that’s no longer the case. If you are 72 or older as of December 31, 2021, please remember to take your RMD by year-end to avoid a penalty (if you are turning 72 in 2021 and this is your first RMD, you have until April 1, 2022). To read about all these year-end strategies in detail, we've included Make Your Final Tax-Saving Moves Before Dec. 31 in our newsletter.
As we close out 2021, we also want to acknowledge the bipartisan Infrastructure Investment and Jobs Act Bill that just passed. The $1.2 trillion bill will fund the building and repairing of roads, bridges, railroads, and ports, as well as make broadband investments throughout the country. If the reconciliation budget comes through in December, which remains to be seen, building and infrastructure initiatives in America will be greater than experienced during the New Deal era. These projects will not begin overnight, so most effects on the economy and investments will be beyond 2022.
The second part of the original bill supports social infrastructure such as healthcare, childcare and housing. The Build Back Better Act proposes an additional $1.2 trillion in spending totaling $3 trillion for both packages. Both sides are still not in agreement on this additional bill. As 2022 begins, we’ll be hearing much commentary on how these bills might influence the economy moving forward. To read more about these bills, we’re sharing the article America has an infrastructure bill. What happens next?
Links are being provided for information purposes only. Raymond James is not affiliated with and does not endorse, authorize or sponsor any of the listed websites or their respective sponsors. Raymond James is not responsible for the content of any website or the collection or use of information regarding any website’s users and/or members. Raymond James does not provide tax or legal services. Please discuss these matters with the appropriate professional.
There is no guarantee that these statements, opinions or forecasts provided herein will prove to be correct. All opinions are as of this date and are subject to change without notice. Past performance is not a guarantee of future results.
Evan Shear Named Member of Raymond James’ 2022 Chairman’s Council
HEATHROW/MERRITT ISLAND, FLORIDA, November 2, 2021 – CrossleyShear Wealth Management (CrossleyShear), a leading financial planning and wealth management firm based in Merritt Island and Heathrow, Florida, announced today that Evan Shear was recently named a member of Raymond James’ 2022 Chairman’s Council.* A privilege limited to a select few, membership in the Chairman’s Council acknowledges Raymond James’ top achieving advisors. The honor of Chairman’s Council status is earned by financial advisors demonstrating the utmost in fiduciary integrity, coupled with a dedication to providing exemplary client-centric care.
“While I’m personally honored to be named to the 2022 Chairman’s Council, this achievement is truly a tribute to our entire CrossleyShear team and their incredible commitment and passion,” stated Evan Shear, Co-Founder and Branch Manager of CrossleyShear Wealth Management, and CERTIFIED FINANCIAL PLANNER™ professional. “Our clients expect and deserve the very best in service and performance. It’s our passion to not only take excellent care of our clients and families, but to provide each with the financial confidence their goals are always within reach, no matter what life brings them. It’s what inspires us on a daily basis. This recognition is a testament to that commitment.”
Evan Shear, together with Dale Crossley, founded CrossleyShear in 1998 and has spent the last 25 years building comprehensive financial plans and providing time-tested wealth management strategies. CrossleyShear manages more than $700 million** in client assets and offers a wide variety of services, including retirement planning, investment and asset management, trust and estate planning, education planning and executive wealth management. The company also serves the complex financial and wealth management needs of sports professionals through CSsports, a division of CrossleyShear Wealth Management.
To learn more about CrossleyShear Wealth Management and the team’s financial planning and wealth management solutions, visit CrossleyShear.com. For more information about CSsports, visit CSsports.net.
About CrossleyShear Wealth Management | Since 1998, CrossleyShear Wealth Management has served as a premier financial planning team dedicated to helping provide clients and families with innovative financial solutions and wealth management strategies. With offices in Heathrow and Merritt Island, Florida, the company’s tailored customer care philosophy and customized planning process helps empower its clients to achieve their financial goals and financial independence. Their professional athlete division, CSsports, is exclusively dedicated to serving the unique needs of sports professionals before, during and after their playing careers. Visit CrossleyShear.com and CSsports.net to learn more.
About Raymond James Financial Services
Raymond James Financial Services, Inc., is a financial services firm supporting more than 4,300 independent financial advisors nationwide. Since 1974, Raymond James Financial Services Inc., member FINRA/SIPC, has provided a wide range of investment and wealth planning related services through its affiliate, Raymond James & Associates, Inc., member New York Stock Exchange/SIPC. Both broker/dealers are wholly owned subsidiaries of Raymond James Financial, Inc. (NYSE-RJF), a leading diversified financial services company with approximately 7,900 financial advisors throughout the United States, Canada and overseas. Total client assets are $824 billion*.
Trust services offered through Raymond James Trust, N.A., a subsidiary of Raymond James Financial, Inc. CrossleyShear Wealth Management and CSsports are not registered broker dealers and are independent of Raymond James Financial Services. Securities offered through Raymond James Financial Services, Inc. Member FINRA/SIPC.
*Membership is based on prior fiscal year production. Re-qualification is required annually. The ranking may not be representative of any one client’s experience, is not an endorsement, and is not indicative of an advisor’s future performance. No fee is paid in exchange for this award/rating.
**As of 10/20/2021.
Investment advisory services are offered through Raymond James Financial Services Advisors, Inc. Certified Financial Planner Board of Standards Inc. owns the certification marks CFP®, CERTIFIED FINANCIAL PLANNER™, CFP® (with plaque design) and CFP® (with flame design) in the U.S., which it awards to individuals who successfully complete CFP Board’s initial and ongoing certification requirements.
1515 International Parkway, Suite 2019, Heathrow, FL 32746 | 407.215.7575
2395 N. Courtenay Parkway, Suite 201, Merritt Island, FL 32953 | 321.452.0061
Securities are offered through Raymond James Financial Services, Inc., member FINRA/SIPC. Investment advisory services offered through Raymond James Financial Services Advisors, Inc. CrossleyShear Wealth Management is not a registered broker/dealer and is independent of Raymond James Financial Services.
Chicken Cacciatore
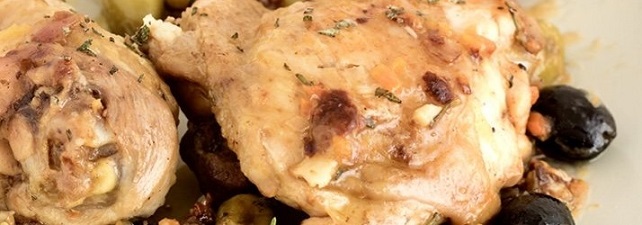
Cooking time 30 minutes
Serving size 4-6
Difficulty level Easy
Chicken Cacciatore
In Italian cuisine, “alla cacciatora” refers to a meal prepared “hunter-style”, a rustic style. In fact, it comes from the tradition of farmers and hunters, which was and is still based on the consumption of their own products they grow and produce. So many regions from the centre of Italy claim to have originated this dish, which really varies among them. For instance, some use tomato sauce, some not. We won’t tell you we are giving you the ‘national’ recipe, but of course we are giving you the Roman one, which we definitely believe, but don’t tell this to a Tuscan, is the most authentic.
Ingredients
1.5 kg (3.5 lbs) whole chicken with skin (you can also buy chicken pieces, bone in, skin on)
250 gr (8.8 oz) pitted green olives
2 medium-sized red onions
180 gr (6.3 oz) salted capers
½ cup of table white wine
3 rosemary sprigs
EVOO
Mediterranean Sea Salt
Ground black pepper
Setting up:
Finely chopped onions, capers and olives.
Directions
If using a whole chicken, cut into thighs, legs and breasts.
Heat a large sauté pan. Brown the chicken, and as soon as a golden patina is reached on both sides, add EVOO, finely chopped onions, capers, olives and rosemary sprigs. Stir it. Pour in the white wine and let it blend into the sauce. Once the alcoholic part has been reduced, season with salt and ground black pepper, stir and then cook over medium heat for about 15 minutes.
This dish perfectly pairs with Chianti DOCG
Article printed from LA CUCINA SABINA: https://www.lacucinasabina.com
URL to article: https://www.lacucinasabina.com/recipe/chicken-cacciatore/
Links are being provided for information purposes only. Raymond James is not affiliated with and does not endorse, authorize or sponsor any of the listed websites or their respective sponsors. Raymond James is not responsible for the content of any website or the collection or use of information regarding any website’s users and/or members. Raymond James does not provide tax or legal services. Please discuss these matters with the appropriate professional.
Links are being provided for information purposes only. Raymond James is not affiliated with and does not endorse, authorize or sponsor any of the listed websites or their respective sponsors. Raymond James is not responsible for the content of any website or the collection or use of information regarding any website’s users and/or members. Raymond James does not provide tax or legal services. Please discuss these matters with the appropriate professional.
Make Your Final Tax-Saving Moves Before Dec. 31
Make Your Final Tax-Saving Moves Before Dec. 31
Proactive investors know that the months before year-end can be an ideal time to make strategic adjustments.
While keeping in mind your long-term investment goals, meet with your advisor and coordinate with your tax professional to examine nuances and changes that could impact your typical year-end planning.
Mind your RMDs
Be thoughtful about required minimum distributions (RMDs) to ensure that you comply with the rules – especially as some of those rules have shifted throughout the course of the pandemic.
Last year, the CARES Act waived all RMD obligations. But for 2021, requirements are back to normal. Investors that reach a certain age – 70 1/2 for those born before July 1, 1949; 72 for those born after – are required to take RMDs from their IRAs. You’ll face a hefty 50% tax penalty on amounts not withdrawn from your IRA to meet the RMD, so be sure to speak with your advisor to ensure you’ve met your obligations.
A few reminders for future distribution planning:
- RMDs can be automated with your advisor to help ensure you don’t miss applicable deadlines.
- Your first RMD can be delayed until April 1 of the year after you turn 72. If you delay, however, you must also take your second RMD in the same tax year. This can inflate your income, which may affect your tax bracket.
- Subsequent RMDs must be taken no later than December 31 of each calendar year.
- Qualified charitable distributions allow traditional IRA owners who transfer RMDs to qualified charities to exclude the amount donated from their adjusted gross incomes, up to $100,000.
- Be mindful of how taking a distribution will impact your taxable income or tax bracket. If you have space left in your bracket or a down income year, you may want to consider taking additional distributions.
To harvest or not to harvest
Evaluate whether you could benefit from tax-loss harvesting – selling a losing investment to offset gains. The first $3,000 (single or married filing jointly) offsets ordinary income. Excess losses also can be carried forward to future years. With your advisor, examine the following subtleties when aiming to decrease your tax bill:
- Short-term gains are taxed at a higher marginal rate; aim to reduce those first.
- Don’t disrupt your long-term investment strategy when harvesting losses.
- Be aware of “wash sale” rules that affect new purchases before and after the sale of a security. If you sell a security at a loss but purchase another “substantially identical” security – within 30 days before or after the sale date – the IRS likely will consider that a wash sale and disallow the loss deduction. The IRS will look at all your accounts – 401(k), IRA, etc. – when determining if a wash sale occurred.
Manage your income and deductions
Those at or near the next tax bracket should pay close attention to anything that might bump them up and plan to reduce taxable income before the end of the year.
- Determine if it makes sense to accelerate deductions or defer income, potentially allowing you to minimize your current tax liability. Some companies may give you an opportunity to defer bonuses and so forth into a future year as well.
- Certain retirement plans also can help you defer taxes. Contributing to a traditional 401(k) allows you to pay income tax only when you withdraw money from the plan in the future, at which point your income and tax rate may be lower or you may have more deductions available to offset the income.*
- Evaluate your income sources – earned income, corporate bonds, municipal bonds, qualified dividends, etc. – to help reduce the overall tax impact.
Evaluate life changes
From welcoming a new family member to moving to a new state, any number of life changes may have impacted your circumstances over the past year. Bring your financial advisor up to speed on major life changes and ask how they could affect your year-end planning.
- Moving can significantly impact tax and estate planning, especially if you’ve relocated from a high income tax state to a low income tax state, from a state with a state income tax to one without (or vice versa), or if you’ve moved to a state with increased asset protection. Note that moving expenses themselves are no longer deductible for most taxpayers.
- Give thought to your family members’ life changes as well as your own – job changes, births, deaths, weddings and divorces, for example, can all necessitate changes – and consider updating your estate documents accordingly.
Next steps
Consider these to-dos as you prepare to make the most of year-end financial moves, and discuss with your financial advisor and tax professional:
- Manage your income and deductions, paying close attention to your marginal tax bracket.
- Evaluate your investments, keeping in mind whether you could benefit from tax-loss harvesting.
- Make a list of the life changes you and your family have experienced during the year.
*Withdrawals prior to age 59 1/2 may also be subject to a 10% federal penalty tax. RMDs are generally subject to federal income tax and may be subject to state taxes. Consult your tax advisor to assess your situation. Raymond James does not provide tax or legal services. Please discuss these matters with the appropriate professional.
Links are being provided for information purposes only. Raymond James is not affiliated with and does not endorse, authorize or sponsor any of the listed websites or their respective sponsors. Raymond James is not responsible for the content of any website or the collection or use of information regarding any website’s users and/or members. Raymond James does not provide tax or legal services. Please discuss these matters with the appropriate professional.
Trading vs. Investing… Growing vs. Protecting
Trading vs. Investing... Growing vs. Protecting
Doug Drabik discusses fixed income market conditions and offers insight for bond investors.
Trading and investing (as it pertains to bonds held in your investment portfolio) may seemingly be equivalent but they are inherently quite different. Trading is tactical and results often rely on dynamic timing, accurate forecasting and economic data attentiveness. Expected possible consequences to more volatile trading are potentially greater gains but also greater losses. Investing is much less active, often strategically long-term and significantly more predictable. Fixed income disciplinary disciples often utilize bonds as investments, not trading vehicles.
There are numerous “distractions” amplified by drama-driven media outlets that can be disruptive forces when investing. It may be inefficient to underestimate the power of fear and emotion on economic conditions. Take for example the 2020 pandemic. Is your garage or basement chockfull of toilet paper, hand sanitizer or paper towels? The fear of running out initiated a hoarding of goods. The hoarding of goods contributed to the shortage itself. Some folks had plenty of supply while others had none.
Now think of the current supply chain issue. When a corporation or factory relies on a particular material for production of their product, fear of a shortage or logistic problems amplify the supply deficiency when they amass greater than needed materials. Some stores over-stock while others are left slighted and disadvantaged.
The Federal debt-ceiling is another current distraction. Although the Senate approved legislation late last week to raise the debt ceiling, it is a short-term fix that kicks the can down the road for two months before it resurfaces again. This self-imposed legislative rule was created by Congress, and can be eliminated by Congress or amended at any time by congress. The notion that Congress would ever let our U.S. debt default over an arguably political-based rule used more for political grandstanding than as a useful economic tool, is absurd. Yet, this distraction periodically induces market movement.
The common denominator is that momentary distractions may affect trading decisions but rarely should alter fixed income investing. Successful trading relies on timing the market in anticipation that opportune appreciation contributes to income generation. Investing is not about timing the market, but about time in the market. Distractions escalate and diminish recurrently, yet strategic long-term individual bonds perform their task of principal protection irrespective of the commotion or momentary distractions.
To learn more about the risks and rewards of investing in fixed income, please access the Securities Industry and Financial Markets Association’s “Learn More” section of investinginbonds.com, FINRA’s “Smart Bond Investing” section of finra.org, and the Municipal Securities Rulemaking Board’s (MSRB) Electronic Municipal Market Access System (EMMA) “Education Center” section of emma.msrb.org.
The author of this material is a Trader in the Fixed Income Department of Raymond James & Associates (RJA), and is not an Analyst. Any opinions expressed may differ from opinions expressed by other departments of RJA, including our Equity Research Department, and are subject to change without notice. The data and information contained herein was obtained from sources considered to be reliable, but RJA does not guarantee its accuracy and/or completeness. Neither the information nor any opinions expressed constitute a solicitation for the purchase or sale of any security referred to herein. This material may include analysis of sectors, securities and/or derivatives that RJA may have positions, long or short, held proprietarily. RJA or its affiliates may execute transactions which may not be consistent with the report’s conclusions. RJA may also have performed investment banking services for the issuers of such securities. Investors should discuss the risks inherent in bonds with their Raymond James Financial Advisor. Risks include, but are not limited to, changes in interest rates, liquidity, credit quality, volatility, and duration. Past performance is no assurance of future results.
Stocks are appropriate for investors who have a more aggressive investment objective, since they fluctuate in value and involve risks including the possible loss of capital. Dividends will fluctuate and are not guaranteed. Prior to making an investment decision, please consult with your financial advisor about your individual situation.
Links are being provided for information purposes only. Raymond James is not affiliated with and does not endorse, authorize or sponsor any of the listed websites or their respective sponsors. Raymond James is not responsible for the content of any website or the collection or use of information regarding any website’s users and/or members. Raymond James does not provide tax or legal services. Please discuss these matters with the appropriate professional.