Archive for the ‘Newsletter’ Category
CrossleyShear Wealth Management's Media
The future of Social Security: What you need to know today
The future of Social Security: What you need to know today
Retirement & Longevity
How Social Security’s anticipated shortfall may impact you down the road
Social Security’s outlook continues to raise concerns. Amid talk of insolvency, understanding the status of the program and the options legislators have for addressing its challenges is key for anyone planning for retirement.
First, Social Security is not at risk of bankruptcy. Social Security benefits are funded by payroll taxes collected from today’s workers. It’s a pay-as-you-go system; if workers and business owners are paying payroll taxes, Social Security benefits will be paid.
Insolvency projections and the potential for benefits to be reduced, however, are related to the nation’s changing demographics and the depletion of a reserve fund that for years has helped offset a revenue shortfall.
According to the 2026 Social Security financial report, the reserve fund – specifically the Social Security Old-Age and Survivors Insurance trust fund – is expected to be depleted by the end of 2032. If Congress does not act, incoming revenue would be enough to cover only 78% of benefits, a reduction of 22%.
A separate trust fund, which backstops Social Security disability benefits, is projected to last until 2100.
The program’s long-term outlook continues to evolve as economic conditions, tax policies and legislative actions develop. As a result, projections regarding future benefit payments and reserve depletion may shift from year to year.
For decades, the Social Security system collected more in payroll taxes and other income than the benefits it paid out, creating a reserve. Since the early 2010s, when the program’s costs began exceeding its revenue, it started drawing from reserves.
Today’s baby boomers have a greater life expectancy than those in earlier generations. At the same time, younger generations are getting smaller, meaning fewer workers are paying into Social Security. And a smaller percentage of Americans’ income is subject to the payroll taxes funding Social Security because the earnings of the highest-paid workers have grown faster than those of the average worker.
Sixty-eight million Americans receive Social Security payments each month – it’s the main source of income for people 65 and older – making its future important. To patch the shortfall, Congress has some options.
Option 1: Increase tax revenue
The most obvious way to increase Social Security funding is raising payroll taxes. Employers and employees currently each pay 6.2% for social security, resulting in a total contribution of 12.4%. Increasing the contribution shared between employers and employees could ensure solvency for many years but may be unaffordable for lower-income workers.
Another option is adding new tax sources. The American Academy of Actuaries has suggested taxing investment income or increasing estate and gift taxes – an idea likely to face resistance.
Additionally, the Social Security tax rate applies to annual wages up to $184,500. Removing that cap and taxing all earned income could eliminate a majority of the shortfall, though the cap was designed to prevent higher taxation that may not justify the benefits. Social Security’s political support comes from the idea that you can receive back a benefit you have paid into; removing the cap could undermine that support.
Option 2: Reduce benefits for high earners
Another idea is to reduce future benefits for high earners not yet collecting Social Security, based on the assumption they’ll rely on it less. But this alone wouldn’t curb Social Security expenditures enough to address the problem.
Option 3: Raise the retirement age
Today the full retirement age (FRA) is 66 and two months for those born in 1955, gradually increasing to 67 for anyone born in 1960 or later. Some lawmakers propose raising the FRA to 70 to reflect today’s longer life expectancy. This alone could eliminate nearly a third of the Social Security trust fund’s 75-year deficit. However, working to an older age could be especially challenging for low-income Americans and those in physically demanding jobs.
No easy answers
Odds are a solution would comprise some combination of these actions – higher taxes for some, lower benefits for some, more years on the job for some. And any proposal is likely to face opposition. The sooner policymakers act, the more options they will have, and the more time pre-retirement Americans will have to prepare for changes.
While headlines about funding can create uncertainty, they should not affect decisions about when to file. That strategy should be grounded in your goals, including income needs, health and life expectancy.
Links are being provided for information purposes only. Raymond James is not affiliated with and does not endorse, authorize or sponsor any of the listed websites or their respective sponsors. Raymond James is not responsible for the content of any website or the collection or use of information regarding any website’s users and/or members. Raymond James does not provide tax or legal services. Please discuss these matters with the appropriate professional.
From the Desk of Dale Crossley and Evan Shear
From the Desk of Dale Crossley and Evan Shear | 2026
We hope this newsletter finds you and your loved ones well. It’s been quite a summer. Between unsettling headlines, geopolitical tensions, and even questions about whether it’s safe to eat lettuce, uncertainty seems to be everywhere.
While the markets can feel as though they’re changing by the day, or even by the hour, our commitment remains constant: to be a steady, trusted partner in your financial planning. Part of that commitment is keeping you informed, so we’d like to share a few timely financial planning updates, along with the latest news from our team.
Back-To-School and Trump Accounts
Back-to-school season has a way of getting families thinking about the future. College may be years away for some, while others are already watching the first day of kindergarten or even welcoming a new baby. Whatever stage your family is in, starting early can make a meaningful difference when it comes to saving and investing for the years ahead.
One newer option families may be hearing about are Trump Accounts, tax-advantaged investment accounts designed for children under age 18. Families can contribute up to $5,000 per year, and eligible U.S. citizen children born between January 1, 2025, and December 31, 2028, can receive a one-time $1,000 contribution from the U.S. Treasury. The money is invested for long-term growth, giving families another way to begin building a financial foundation for their children.
Beyond the dollars themselves, we like the idea of getting children involved in conversations about saving and investing from an early age. Watching an account grow over time can provide an opportunity to introduce important financial concepts and help children begin developing good financial habits.
Once the child turns 18, the account becomes theirs. They can continue investing for the future or access the funds, subject to the rules and tax treatment that apply to traditional IRAs.
For families with young children, or even a new addition on the way, Trump Accounts may be worth learning more about as part of a broader financial strategy. They aren’t intended to replace other planning tools, but they can provide another opportunity to start early and give the next generation a head start.
It’s important to note that Trump Accounts are established and managed through the federal government’s official Trump Accounts platform, not through CrossleyShear or your financial advisor. While we cannot open or manage a Trump Account on your behalf, we can help you consider how this new savings option may fit within your family’s broader financial plan.
Team Spotlight
Please join us in congratulating Shaun Jones on earning his CFP® (CERTIFIED FINANCIAL PLANNER PROFESSIONAL™) designation!
Widely recognized as the gold standard in financial planning, the CFP® designation reflects a rigorous commitment to education, professional excellence, and ethical conduct. As a CFP® professional, Shaun is committed to upholding the CFP Board’s Code of Ethics and Standards of Conduct, including disclosing conflicts of interest, maintaining confidentiality, and, above all, acting as a fiduciary in our clients’ best interests.
Earning this designation is a significant milestone in Shaun’s career and a testament to the hard work and dedication he has invested in serving our clients. It also strengthens the CrossleyShear team with additional bench strength, providing the thoughtful, knowledgeable advice our clients have come to expect. We’re incredibly proud of Shaun and congratulate him on this exciting achievement!
WorthWhile Magazine
Have you been reading WorthWhile Magazine? We’ve found that it lives up to its name.
The summer issue celebrates the magazine’s 20th anniversary with a wide variety of timely and thought-provoking articles. Among the highlights is a celebration of America 250, featuring inventions and ideas that originated right here in the United States. You’ll also find articles exploring sibling dynamics, the evolution of Roth IRAs, and the ways AI is reshaping the workplace.
The issue also takes a look at wellness retreats and the changing landscape of destination weddings, offering something for just about every interest.
We think it’s definitely worth your while to check out.
And as always, if something you read sparks a question about your own financial plans, we’re here to help. Whether you’re planning for the future, navigating a life change, or simply looking for a second opinion, contact CrossleyShear today. Our team is here to provide thoughtful guidance at every stage of life.
Any opinions are those of CrossleyShear Wealth Management and not necessarily those of Raymond James. The information has been obtained from sources considered to be reliable, but we do not guarantee that the foregoing material is accurate or complete. Links are being provided for information purposes only. Raymond James is not affiliated with and does not endorse, authorize or sponsor any of the listed websites or their respective sponsors. Raymond James is not responsible for the content of any website or the collection or use of information regarding any website’s users and/or members.
There is no guarantee that these statements, opinions or forecasts provided herein will prove to be correct. All opinions are as of this date and are subject to change without notice. Past performance is not a guarantee of future results.
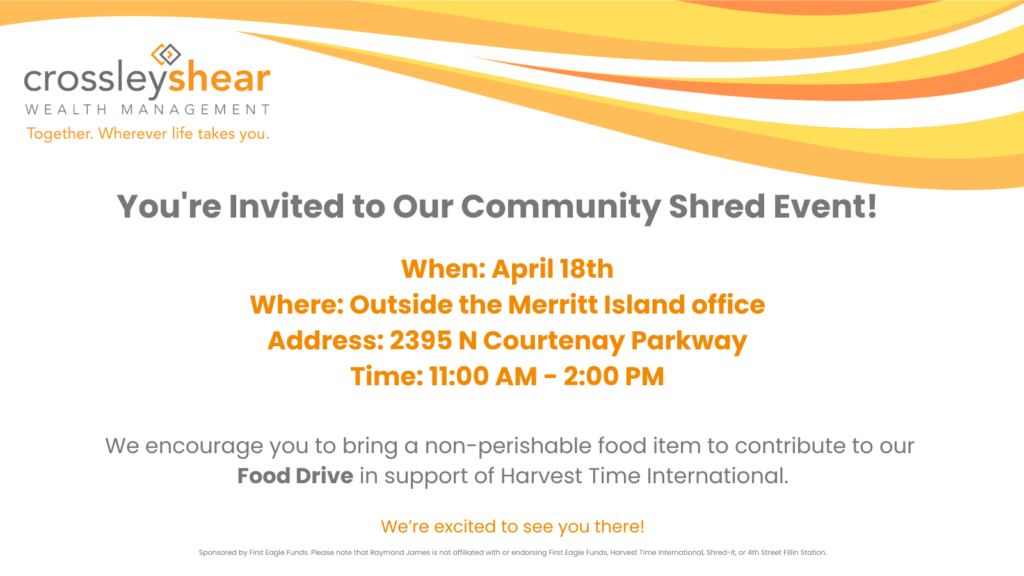
Hope you can join us!
Links are being provided for information purposes only. Raymond James is not affiliated with and does not endorse, authorize or sponsor any of the listed websites or their respective sponsors. Raymond James is not responsible for the content of any website or the collection or use of information regarding any website’s users and/or members. Raymond James does not provide tax or legal services. Please discuss these matters with the appropriate professional.
For Better or Worse, Discuss Your Estate as a Couple
For Better or Worse, Discuss Your Estate as a Couple
Are you making the transition into married life? Consider these five estate planning to-do’s as you start your life together.
Wedding season, which typically runs from late spring through early fall, is officially upon us. If you are engaged or newly married, consider discussing your estate planning intentions with your partner and a trusted advisor. While it’s easy to get wrapped up in finding the perfect dress or finalizing your guest list, you should also be planning for the life changes to come after the ceremony. Not only will this help prepare you for the road ahead, but it can also allow you to begin cultivating your estate as a couple.
Once you and your partner schedule a meeting with your advisor, you can begin by discussing these five estate planning moves, which should be addressed before or as soon as you head down the aisle:
Update your beneficiary designations. To make your new spouse the beneficiary of your life insurance or retirement accounts, you’ll likely need to visit your employer’s HR department and complete the necessary forms.
Review your life insurance needs. Have you spoken to your partner about what would happen if one of you passed away unexpectedly? For instance, if you own a home together and your spouse passed away, could you pay the mortgage with only one income? These questions can be difficult, but it’s important to consider whether your current life insurance still meets your needs – particularly if you have children or are planning to start a family in the near future.
Execute your wills. The last thing on your mind if facing the devastating loss of your spouse is the legal minutiae. But you should know that while many states will rule that, in the absence of a will, all assets revert to the surviving partner, this is not always the case. Sadly, if your spouse dies without a will, you could endure the delay and expense of probate to determine what assets you may receive, all while you are grieving. In some cases, the state will even designate certain assets to parents or loved ones of the deceased spouse. As tough as it is, these conversations are incredibly important. Keep in mind, too, that your will and estate plan must reflect the same provisions of any prenuptial agreement in the event of your partner’s death.
Consider establishing durable powers of attorney and advanced healthcare directives. Double check to make sure your partner is authorized to make medical, legal, or financial decisions on your behalf – not all states automatically grant spouses that authority. As you move into married life, ask those important questions and understand the decisions you might have to make for one another in the unfortunate event something unthinkable happens.
Discuss your homeownership documents. Does one of you already own a home you will be sharing? Or, are you thinking about buying a home together? Consider your living situation as a couple and speak with your advisor about investigating strategies that include joint property and tenancy by the entirety, as well as state homestead laws and where to properly record deeds and other real estate documentation.
A wedding is an unforgettable event. But given all the time and expense that goes into preparing for the big day, it’s important that you dedicate some of those resources to planning for your future as a couple. These ideas will help you get the ball rolling on these important conversations to have with your financial advisor and your partner.
Raymond James and its advisors do not offer legal advice. You should discuss any legal matters with the appropriate professional.
Links are being provided for information purposes only. Raymond James is not affiliated with and does not endorse, authorize or sponsor any of the listed websites or their respective sponsors. Raymond James is not responsible for the content of any website or the collection or use of information regarding any website’s users and/or members. Raymond James does not provide tax or legal services. Please discuss these matters with the appropriate professional.
Travel securely: Keep your information protected on the go
Travel securely: Keep your information protected on the go
Learn about a few simple things you can do to protect your personal information while you travel.
Travel can be one of life’s great pleasures, especially when you’re enjoying retirement. Exploring new-to-you countries or revisiting favorite spots is fulfilling, whether traveling by yourself or with family or friends. Regardless of who you travel with, there can be the risk of an unwanted guest – in the form of threats to your personal information.
In the age of smartphones and abundant Wi-Fi hotspots, it’s important to remember that your information travels with you. That’s why ensuring your devices, as well as your credit and debit cards, are secure when you travel abroad is vital. Fortunately, there are precautions you can take to help minimize the threat of your sensitive data being compromised.
Be mindful of your device settings
When traveling, consider disabling certain settings on your devices, like Bluetooth and your laptop’s webcam. Use Wi-Fi only through a trusted source rather than a public or unknown source and make sure your device doesn’t try to automatically connect to networks when you aren’t using it.
Think about using a virtual private network (VPN) while traveling. A VPN helps to keep your personal information, browsing history and location private so you can use your devices more securely on the road. There are numerous providers available for purchasing VPN services, so you can explore the features that will work best for your circumstances.
Limit your account access while traveling
It's also important to be mindful of the websites you’re accessing while traveling. Even when using a VPN, try to avoid accessing web accounts that contain any sensitive information, such as your financial, personal or health information. If you do need to access any such accounts, consider changing your passwords when you arrive home as an added security measure.
Keep in mind that any devices you might use that are not your own are especially unlikely to be secure. Public computers, such as those in a hotel common workspace or an internet café, pose an additional risk to your information. Looking up museum hours or directions to your dinner reservations is one thing, but it’s best not to use any sort of public computer for anything you need to supply a password to access.
Think about what you’re taking with you
Consider which of your electronic devices you’re taking with you while you travel, and which you may be able to leave at home. For example, leave your laptop at home if you can, especially if you’re traveling for pleasure rather than business. Likewise with your credit cards and any important documents – take only what you need and make sure you’re carrying them securely.
Be prepared to verify purchases if needed
It’s always a good idea to make sure your financial institution knows that you’ll be traveling so your purchases aren’t flagged as fraudulent. You may still be notified about suspicious charges, however, as stolen or counterfeit cards are always a risk.
Check with your credit card company before you travel to learn the process for approving any charges the company may flag as fraudulent, so you know what to expect. Debit cards also often have daily limits on ATM withdrawals and point of sale purchases. Certain transactions at high-risk merchants or some transactions identified as potentially fraudulent may also require additional verification from the merchant. It’s good to be aware of all of this before your trip.
Next steps
Here are a few more tips for traveling securely:
- Use ATMs inside banks whenever possible and avoid standalone ATMs.
- Pay attention to the card reader. If it is loose or appears to be tampered with, do not use that ATM.
- If you lose a card, report the loss to your financial institution immediately.
Links are being provided for information purposes only. Raymond James is not affiliated with and does not endorse, authorize or sponsor any of the listed websites or their respective sponsors. Raymond James is not responsible for the content of any website or the collection or use of information regarding any website’s users and/or members. Raymond James does not provide tax or legal services. Please discuss these matters with the appropriate professional.