Archive for the ‘Newsletter’ Category
CrossleyShear Wealth Management's Media
What if I Haven’t Updated My Estate Plan in Years?
What if I Haven’t Updated My Estate Plan in Years?
It’s tempting to create an estate plan and assume the job is finished. However, as life changes, an estate plan that hasn’t been reviewed in years may no longer reflect your current family situation, financial circumstances, or wishes.
Periodically reviewing your estate plan is an important part of an overall financial plan, helping you identify common life changes that signal it’s time for another look.
Life Changes That Trigger a Review
A routine estate plan review should occur every three to five years to accommodate changes in tax laws and evolving personal goals.
That said, it’s important to evaluate and update your estate plan after each major milestone to help ensure your assets and loved ones remain protected.
- Marriage or divorce
- Birth or adoption of a child
- Death of a loved one
- Retirement or major career change
- Relocation to another state
- Significant changes in assets
Review Beneficiary Designations
Beneficiary designations dictate who receives your assets and prevail over any other instructions in your will or trust. As such, it's essential to review how you want your financial assets distributed.
Why Reviewing Beneficiary Designations Matters
- Designations override wills and trusts: You may have changed your will after a divorce, but if you neglected to remove your ex-spouse as the beneficiary on a life insurance policy or retirement account, the financial institution is legally obligated to give the money to the person named on that document.
- Avoiding probate: When your accounts have designated beneficiaries, there’s no need to go through the slow, public probate court process, allowing your loved ones to receive the funds sooner.
- Major life changes: Any major life change should trigger a beneficiary review to ensure you provide for your loved ones.
- Family conflict prevention: Confusion, family conflicts, and costly legal battles often arise in the absence of updated and accurate beneficiary names.
Regularly Review All Legal Documents
In addition to ensuring your beneficiary information is up to date and accurate, it's also important to routinely evaluate the accuracy of your legal documents, including:
- Wills and Trusts: Confirm that guardians for minor children and asset distributions reflect your current intentions.
- Powers of attorney: Verify that the individuals you’ve selected to manage your legal matters—in the event of your incapacitation—are still trustworthy and able to carry out their duties.
- Healthcare directives: Ensure the person chosen as your healthcare spokesperson is still a viable choice, and that you use accurate medical terminology to voice your preferences and end-of-life instructions.
Document Organization and Accessibility
One of the best things you can do to prepare for an emergency is keep important documents organized and easily accessible to your loved ones.
- Keep essential records in a secure, fireproof, and waterproof safe: financial documents, wills, certificates
- Back up all records digitally: provide your trusted representative with access and passwords
How a Financial Advisor Enhances an Estate Planning Team
While your attorney manages the legal framework of updating an estate plan, a knowledgeable financial advisor can help organize your assets and ensure your broader financial plan aligns with your wishes.
- Wealth preservation and tax efficiency strategies
- Coordinated legal and financial planning
- Comprehensive financial guidance
Contact the CrossleyShear team to discuss how we can help coordinate your estate planning goals with your broader financial plan.
Every investor's situation is unique, and you should consider your investment goals, risk tolerance and time horizon before making any investment. Prior to making an investment decision, please consult with your financial advisor about your individual situation. The foregoing information has been obtained from sources considered to be reliable, but we do not guarantee that it is accurate or complete, it is not a statement of all available data necessary for making an investment decision, and it does not constitute a recommendation. Any opinions are those of Dale Crossley and Evan Shear and not necessarily those of Raymond James.
Please note, changes in tax laws may occur at any time and could have a substantial impact upon each person's situation. While we are familiar with the tax provisions of the issues presented herein, as Financial Advisors of RJFS, we are not qualified to render advice on tax or legal matters. You should discuss tax or legal matters with the appropriate professional
City S’mores
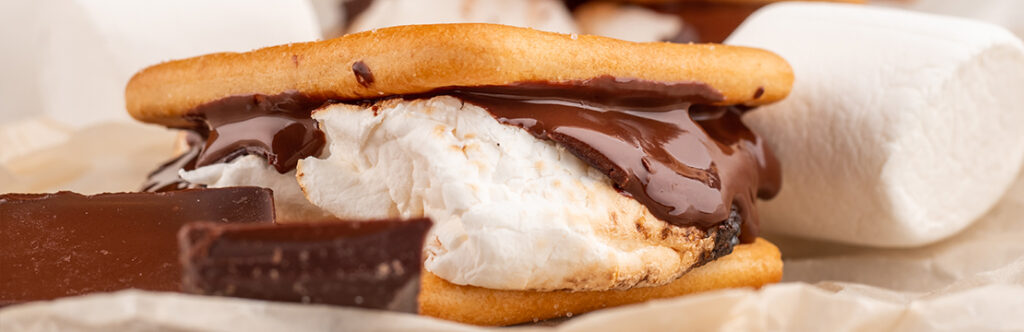
City S'mores ~ By Mandy Evans
Ingredients
- Graham Crackers (broken in half)
- Chocolate Bars (Hershey) broken into 2 pieces
- 1 large marshmallow (cut in half)
- Microwave-safe plate
Step-by-Step Instructions
- Place one graham cracker half on the microwave-safe plate.
- Position the marshmallow directly on top of the cracker.
- Microwave on high for 10 to 15 seconds. Watch closely through the door as the marshmallow will puff up very fast.
- Remove the plate carefully.
- Put chocolate on top of the marshmallow and put the second graham cracker half on top of the puffed marshmallow and press down gently to form a sandwich.
- Repeat until you have as many as you would like
- Refrigerate for at least an hour or until ready to eat.
No sunset yet
No sunset yet
Tax Planning
The “One Big Beautiful Bill Act” brings clarity and opportunity for estate planning.
The new legislation passed last year, known as the “One Big Beautiful Bill Act,” solidified key provisions from the 2017 Tax Cuts and Jobs Act, extending the estate, gift and generation-skipping transfer tax exemptions that were previously set to expire at the end of 2025.
Before the new legislation, many investors were preparing to make large gifts ahead of the deadline to take advantage of the higher exemption before it was cut in half. Now some may feel a sense of relief, but it’s important to remember that a lot can happen in a short time.
While one major uncertainty has been addressed for now, laws and life can change. This new legislation serves as a reminder to review your estate plan and ensure your long-term financial goals are fully supported.
A shift in focus
Even with more certainty around federal tax exemptions, there are still important details to keep in mind, especially if you're thinking about how to help protect and pass on your wealth.
Step-up in basis
With the indefinite extension of the federal estate and gift tax exemption in effect, pressure to “use it or lose it” has subsided for the time being. Even though the lifetime exemption amount is the same whether you use it for gifting during your lifetime or as inheritance through your estate, the way you transfer assets can have a major impact on taxes.
If you gift someone an appreciating asset during your lifetime, they inherit your original cost basis and have to pay capital gains tax on the accrued value. However, if they receive it through your estate, it may get a step-up in basis to its current market value, potentially eliminating capital gains tax.
Estate and gift tax exemption portability
Any unused portion of the combined $30 million estate and gift tax exemption for married couples can transfer to the surviving spouse, allowing them to use the unused exemption, provided the appropriate election is made on the federal estate tax return. While this can increase the total amount of assets eligible for a step-up in basis and exempt from federal estate tax, not all assets qualify. It’s important to plan ahead to understand which assets do and how to best structure the estate.
Generation-skipping transfer tax exemption
A separate exemption of $15 million per person protects assets passed to grandchildren or other skipped-generation beneficiaries from the 40% generation-skipping transfer tax. Unlike the estate and gift tax exemption, it can’t be transferred to a surviving spouse and must be used during one’s lifetime or directed through estate documents. This exemption can be useful for families looking to pass wealth to future generations or set up long-term trusts, together with the estate and gift tax exemption.
OBBBA tax-related highlights for investors
- Solidified gift tax increase to $15 million for individuals, $30 million for married couples
- Generation-skipping transfer tax exemption increased, but remains non-portable
- Current tax brackets extended
Strategic planning and focus
Estate planning is not just about limiting taxes. It’s about asset protection, control and privacy.
For estates valued within the new exemption limits, emphasis on planning shifts from mitigating federal estate tax to focusing on relevant state-level tax implications – which can significantly impact wealth transfer – and broader legacy goals. Regardless of asset size, it’s essential to have foundational estate planning documents in place such as wills, powers of attorney, healthcare directives and privacy protections. For families with minor children or dependents, naming guardians is a critical step to ensure their care and well-being in the event of an untimely loss.
Owners of estates that fall within the expanded portion of the exception amount should consider the possibility of exposure if that amount were reduced, especially if their time horizon includes the next few election cycles. Should the exclusion be reduced in their lifetime, their estate plan should have flexibility in place to help protect assets that would otherwise become subject to federal estate tax. Many states also impose estate or inheritance taxes, which should be considered in overall planning.
For individuals with $30 million or more in liquid assets, estate planning shifts to preserving capital, minimizing tax exposure and helping protect assets and legacy. Strategies like preventing further growth of appreciating assets and their associated tax liabilities through estate freezing and moving assets outside of the estate through the strategic use of trusts will likely remain viable in the future for amounts over the exemption.
Regardless of estate size, all investors can benefit from taking measures to help protect their assets and preserve their legacy for generations to come by ensuring their estate plans remain adaptable.
Additional provisions of the OBBBA, like expanded 529 eligibility and the introduction of a new type of tax-advantaged savings account for children, can serve as additional tools to help transfer wealth to the next generation.
The OBBBA taught us that tax law can change at any time depending on who is responsible for making those laws. What resulted in many things staying the same could just have easily brought significant change, so ensuring that your estate plan is flexible is essential for its ongoing effectiveness. Accounting for the possibility of legislation changes in the future can help you set up beneficiaries and heirs for financial success in accordance with your wishes.
Raymond James does not provide tax or legal services. Please discuss these matters with the appropriate professional.
Four ways to teach your kids about business
Four ways to teach your kids about business
Business Ownership
Set them up for professional – and personal – success.
Whether your children will grow up to be entrepreneurs or to work for someone else, teaching kids early about business helps them establish valuable skills that can serve them in both their professional and personal lives.
Among other things, learning about business can teach kids problem-solving, time management and the importance of planning. It can also help them understand the value of money and hard work, perseverance and risk-taking.
Here are four ways to help set up your child for success – both in the workplace and in life.
1. Teach them financial literacy.
The sooner you educate your kids about money, the sooner they’ll understand the importance of managing and investing their earnings. Talk to them about income and expenses, budgeting and taxes, and show them how you handle your household finances, pointing out the difference between “wants” and “needs.” Let them experience the consequences of their choices – for example, that buying a new video game today means it will take them longer to save up for a skateboard.
2. Let them learn from their mistakes.
It can be tempting to step in to help your children solve their problems, but eventually they’ll need to be able to manage on their own. Allow them to make mistakes while they’re still in the safety of your home and the stakes are low. Help them explore the factors that contributed to the problem – this builds confidence and resiliency and teaches them not to give up when things become difficult.
3. Take them to work with you.
During summer or spring break, bring your child to work with you to experience a normal day at your business. Talk about the jobs they see being done and how these fit into the broader business picture. Let them shadow you and your employees as you explain what you do each day and why. You could even give them tasks to complete – like filing, shredding or making copies – if you feel they’re ready.
4. Have them run their own business.
Experience is the best teacher, so let your children be CEO of their own business, whether it’s a short-term project or a years-long endeavor. Help them identify their marketable skills and create a business plan, determining how much they’ll need to spend and what they can charge for their products or services. Whether it’s mowing lawns, walking dogs, babysitting, or selling lemonade, running their own business helps kids learn the importance of punctuality and professionalism, as well as marketing and customer service.
Nurturing these skills in your kids today can help them become successful adults tomorrow.
Sources: Gohenry.com, Rampton, John. How to Teach Your Kids Entrepreneurship Early in Life, LinkedIn, Nationwide.com
Links are being provided for information purposes only. Raymond James is not affiliated with and does not endorse, authorize or sponsor any of the listed websites or their respective sponsors. Raymond James is not responsible for the content of any website or the collection or use of information regarding any website’s users and/or members. Raymond James does not provide tax or legal services. Please discuss these matters with the appropriate professional.
529s are more than a college savings tool
529s are more than a college savings tool
Estate & Giving
These versatile savings accounts are a powerful estate planning vehicle.
Most of us associate 529 accounts with college savings. They’re flexible, allowing you to transfer assets to anyone, including yourself, for the express purpose of furthering the education of your beneficiary. But did you know that a 529 can be a powerful estate planning tool?
Modern estate planning
These specialized savings accounts have advantages for the beneficiaries – but there are benefits for the donors, too, given the tax advantages and the option to change heirs.
The tax rules that govern these accounts allow you to pare down your taxable estate, potentially minimizing future federal gift and estate taxes.
With 529s, you can make a lump-sum contribution of up to five times the annual limit of $19,000. That means you can gift $95,000 per recipient ($190,000 for married couples), as long as you denote your five-year gift on your federal tax return and do not make any more gifts to the same recipient during that five-year period. However, you can elect to give another lump sum after those five years are up. In the meantime, your investments have the luxury of time to compound and potentially grow.
Other benefits
Many people worry that gifting large chunks of money to a 529 means they’ll irrevocably give up control of those assets. However, 529s allow you quite a bit of control, especially if you title the account in your name. You can change the beneficiary to another member of the family as many times as you like, since most 529s have no time limits.
If your chosen beneficiary receives a scholarship or financial aid, they may not need the money you’ve stashed away in a 529. You can earmark the money for other types of education, like graduate school. Or you can take the money and pay the taxes on any gains. Of course, that means it becomes part of your taxable estate again subject to your nominal federal tax rate, and you’ll have to pay an additional 10% penalty on the earnings portion of the withdrawal. You can always use the funds to pay for other qualified education expenses, like room and board, books and supplies.
Many plans offer you several investment choices, including diversified portfolios allocated among stocks, bonds, mutual funds, CDs and money market instruments, as well as age-based portfolios that are more growth-oriented for younger beneficiaries and less aggressive for those nearing college age.
Saving for college takes discipline, as does estate planning. Talk to your professional advisor about the nuances of different investment strategies and vehicles before making a years-long commitment.
If you’re considering opening a 529:
- Speak to your advisor about how you can maximize the benefits of this specialized savings account.
- Discuss your intentions of the account with your family from an estate planning perspective.
Links are being provided for information purposes only. Raymond James is not affiliated with and does not endorse, authorize or sponsor any of the listed websites or their respective sponsors. Raymond James is not responsible for the content of any website or the collection or use of information regarding any website’s users and/or members. Raymond James does not provide tax or legal services. Please discuss these matters with the appropriate professional.
This material is being provided for information purposes only and is not a complete description, nor is it a recommendation. Prior to making an investment decision, please consult with your financial advisor about your individual situation. Earnings in 529 plans are not subject to federal tax and in most cases state tax, as long as you use withdrawals for eligible education expenses, such as tuition and room and board. However, if you withdraw money from a 529 plan and do not use it on an eligible education expense, you generally will be subject to income tax and an additional 10% federal tax penalty on earnings. As with other investments, there are generally fees and expenses associated with participation in a 529 plan. There is also a risk that these plans may lose money or not perform well enough to cover education costs as anticipated. Most states offer their own 529 programs, which may provide advantages and benefits exclusively for their residents. An investor should consider, before investing, whether the investor’s or designated beneficiary’s home state offers any state tax or other benefits that are only available for investments in such state’s qualified tuition program. Such benefits include financial aid, scholarship funds, and protection from creditors. The tax implications can vary significantly from state to state.